You can be highly educated, earn a good income and still feel completely unprepared to make your first investment decision.
A woman can spend twenty years becoming exceptional at her profession without ever learning how to evaluate an investment.
She might manage a hospital department, run a company, supervise a team or negotiate contracts worth more than her annual salary.
But when someone asks what her retirement account is invested in, she may not know.
That isn’t unusual enough to surprise me anymore.
What concerns me is how easily women interpret unfamiliarity with investing as evidence that they aren’t ready to participate.
They postpone learning until they have more money, less debt, a better salary or more confidence.
Years can pass while the question remains unanswered.
Why do women put off investing?

There isn’t one explanation, and it would be a mistake to assume every woman faces the same obstacles.
For some, money is genuinely tight. Household obligations, caregiving expenses, debt, and inadequate emergency savings can limit the amount available for long-term investing.
Other women have sufficient income but lack familiarity with investment accounts, fees, risk and asset allocation. Fear of losing money can also matter, especially when savings represent years of sacrifice.
Then there’s the woman who already invests through an employer retirement plan but doesn’t understand what she owns. Her next step may not be opening another account. It may be learning about the one she already has.
The distinction matters because a financial problem and an educational problem don’t always require the same solution.
Does a woman need to be wealthy before she starts investing?
No particular income level automatically qualifies someone to begin learning about investing. Whether it makes sense to invest money today is a separate decision.
A woman needs to consider her essential expenses, emergency reserves, expensive debt, time horizon and tolerance for financial risk.
Investing is not a substitute for cash that must remain available for immediate needs.
However, learning about retirement accounts, investment funds, diversification, and fees doesn’t require buying anything.
That is a useful place to begin.
Saving and investing are not the same thing
Saving generally emphasizes access to money and preservation of funds for a particular purpose. Investing involves purchasing assets that may change in value.
Those assets can appreciate, generate income or lose value.
The appropriate choice depends heavily on when the money will be needed.
For example, someone preparing for a major expense next year may need a different approach from a woman investing for retirement twenty years away.
Neither should automatically copy the other’s decisions.
What if you're afraid of losing money?

Fear deserves to be understood rather than dismissed.
A woman who has worked for years to accumulate savings may be understandably protective of them.
The answer isn’t to pretend investment risk doesn’t exist.
It does.
Instead, learn how different investments behave, what diversification can and cannot accomplish, which fees apply and how much loss you could realistically tolerate.
An investment should make sense to you before you commit money to it. Be particularly cautious when someone promises unusually high returns with little or no risk.
That combination deserves scrutiny.
What if you're starting in your 40s or 50s?

Starting later does not mean learning about investing is pointless.
It does mean your financial decisions should reflect the time available before you need the money. You may be in your highest earning years. Perhaps you have substantial retirement savings but haven’t reviewed how they’re allocated. Your family responsibilities might be changing, or you may be rebuilding after a major life event.
A sensible approach starts with your actual circumstances, not a comparison with someone who began investing at 22.
Review what you own, understand your retirement timeline and seek qualified guidance when the decisions require individualized advice.
What if your employer already invests money for you?
Many employees contribute to workplace retirement accounts without understanding their underlying investments.
Start with the account statement.
Identify the account type and review what is held inside it.
Look for information about investment allocation, fees and any employer contributions.
An employer match, when available, is worth understanding because plan rules can affect the value of the benefit.
You may discover that you’ve been investing for years.
Your opportunity is to become more informed about those investments.
What should a beginner learn first?

Begin with the questions that apply to your financial life.
- If you have an employer retirement plan, understand that account.
- If you're considering opening a brokerage account, learn how the account differs from the investments purchased inside it.
Understand common terms such as diversification, expense ratio, asset allocation, index fund and risk tolerance. For authoritative background reading, the U.S.
Securities and Exchange Commission provides investor education through Investor.gov.
FINRA also publishes investor education on accounts, investments, fees, and fraud prevention.
These sources can help you understand concepts before making decisions.
Financial education should increase your ability to ask questions, not pressure you into buying something.
The first $100,000 question
Someone recently asked me how to make and save her first $100,000.
Before answering, I wanted to know what the money was supposed to represent.
A salary of $100,000 isn’t the same as having $100,000 in savings.
Neither is necessarily the same as owning an investment portfolio worth $100,000.
And net worth considers assets minus liabilities.
If your goal involves investing, you need to understand how much you can reasonably contribute, the purpose of the money and the risks you’re accepting.
The number is meaningful only when you understand what you’re building.
What I want professional women to stop doing
I want us to stop treating financial knowledge as something we should have acquired automatically along with our education and professional success.
Those skills are not interchangeable.
Being an excellent nurse doesn’t automatically teach you how a mutual fund works.
Managing a successful company doesn’t mean you know how to evaluate your personal retirement investments.
And not understanding a financial term does not make you less capable.
It means you’ve identified something to learn.
That’s a much more useful conclusion.
Where can women learn about investing without feeling embarrassed?
This is one reason I created Financial Feminism.
I wanted a place where women could ask practical questions about money, careers, business and ownership without feeling they had to prove how much they already knew.
Inside the Financial Feminism Resource Hub, women can explore topics based on what they’re trying to accomplish.
The existing Ownership Ladder™ Assessment helps members consider their current position.
Money, Explained provides plain English definitions across investing, banking, compensation, business, taxes, real estate and other financial topics. And the community creates space to discuss what women are learning.
We’re beginning a 30 Day Ownership Conversation with one question:
What has kept you from investing?
Perhaps your answer is fear. You might need more accessible savings first.
Maybe you don’t understand the account you already have. Whatever the answer, I want you to start with a question that actually belongs to your financial life.
Your next move

Don’t purchase an investment simply because you’ve finished reading an article. Choose one useful action.
Review an existing account statement. Learn what an unfamiliar term means.
Check whether your employer offers retirement contributions.
Understand your current savings needs.
Or ask a question you’ve been avoiding.
Then join us inside Financial Feminism.
Membership is free, and the conversation is open to women at different stages of their financial lives.
You don’t need to feel wealthy to begin becoming financially informed.
Bring your investing question into the Financial Feminism Community.
About the Author
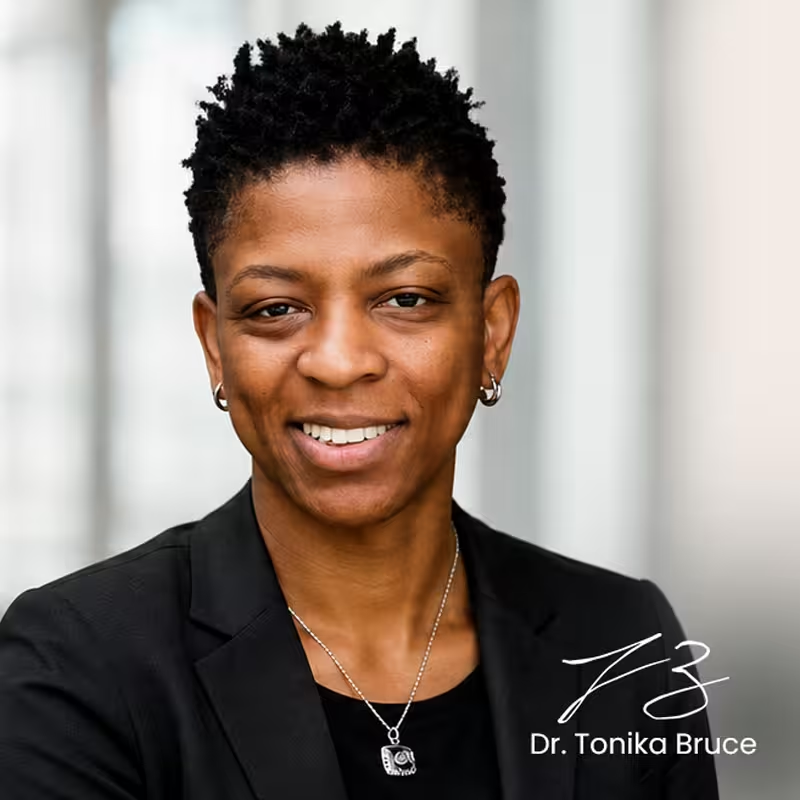
Dr. Tonika Bruce is a business executive, healthcare leader, entrepreneur, leadership strategist and founder and host of Financial Feminism. Her work connects career development, business leadership and financial ownership, helping women examine how their earnings can support greater choices and long-term security.
This article provides general financial education, not individualized investment advice. Investment decisions involve risk and should reflect personal financial circumstances.