GOOD INCOME. REAL CAREER. STILL IN DEBT.
There may be more to the story.
You make good money.
Maybe considerably more than you made five or ten years ago.
You have a career people respect. Your bills get paid. You know how to handle responsibility. From the outside, your financial life may look perfectly fine.
Then you see the credit card balance.
Or the personal loan.
Or the student loan that has followed you through several promotions.
And a question shows up that you probably don’t say out loud:
Why am I still in debt when I make good money?
It can be an uncomfortable question because income carries expectations.
Once you reach a certain salary, you expect money to become easier.
Some things do.
But a higher income does not automatically repair the financial system underneath it.
Old balances can follow new salaries.
Expenses can rise.
Emergencies happen.
Families need help.
Interest keeps moving.
A business can need money.
A divorce can change everything.
Sometimes spending simply grows faster than income.
So before deciding that your debt proves you are irresponsible, look at what the numbers are actually telling you.
There is a much more useful conversation to have.
THE SHORT ANSWER
Why Can You Still Be in Debt With a Good Income?

A good income increases your financial capacity, but it does not automatically eliminate debt. Existing balances, interest, spending, insufficient savings, family obligations, emergencies, lifestyle changes and recurring use of credit can all keep debt alive even after earnings increase.
The real question is not simply how much do you make?
Ask:
What created the debt, and what is keeping it alive now?
Those answers can be completely different.
And that difference is where things get interesting.
A Bigger Paycheck Cannot Fix a System It Doesn't Understand
Imagine receiving a $20,000 raise.
It feels substantial. Then life adjusts.
The nicer apartment suddenly seems reasonable. The car gets upgraded. You travel differently. Convenience gets easier to purchase. Subscriptions multiply. Dinner becomes delivery because you’re working late. You start helping family a little more.
None of those decisions alone looks catastrophic.
Then the additional income is gone.
This is one reason income growth does not always produce the financial progress we expect.
The problem isn’t necessarily that you earn too little.
Your money may simply have acquired more jobs. That deserves attention. Not judgment.
There is also another possibility. Your income increased, but you’re still paying for an earlier version of your life. That credit card balance may have been created before the promotion. The student loan predates your current salary. A personal loan may trace back to a move, relationship change or difficult year.
Today’s paycheck and yesterday’s debt can occupy the same financial life.
The question is what you do with that information.
Stop Asking the Balance to Tell You Who You Are

Debt is excellent at telling you certain things.
It can tell you how much you owe. It can show you the interest rate.
Your statement can tell you the minimum payment.
What debt cannot reliably tell you is whether you are intelligent, disciplined, successful or worthy.
A $12,000 balance doesn’t come with a biography.
One woman may have accumulated it through repeated overspending. Another used credit during unemployment. Someone else helped support family. Another financed education. One started a business. Another never built enough emergency savings, so every unexpected expense landed on a card.
The number can be identical. The financial problem can be completely different.
That is why the first move should not always be:
Pay it off as fast as humanly possible.
First understand what you’re trying to fix.
Meet The Debt Autopsy™
I created The Debt Autopsy™ for a simple reason.
Women need a way to investigate debt without immediately turning the investigation into a trial of their character.
The framework asks four questions:
01. What created it?
02. What is keeping it alive?
03. What is it costing me now?
04. What needs to change?
That’s it. Four questions. But the answers can completely change the plan.
Question One:
What Created the Debt?
Choose one debt.
Not every financial decision you’ve made since college.
One.
Now ask what actually created it.
The easy answer is:
“I spent money.”
Of course you did.
Debt usually involves spending money.
That isn’t specific enough to help you.
What happened?
Perhaps the balance grew during a period of unemployment. Maybe your income never comfortably covered your lifestyle. A move cost considerably more than expected. You supported a family member. A relationship ended. You launched a business before having enough capital. Irregular expenses kept catching you unprepared. Perhaps you simply spent too much.
That answer is allowed too. Financial ownership doesn’t require us to turn every poor decision into a beautiful story about survival.
Sometimes the answer is:
I bought things I couldn’t afford.
Good.
Now we have information.
And information is much more useful than shame.
Question Two:
What Is Keeping It Alive?
This may be the most overlooked question.
The thing that created the debt may be gone.
The thing keeping it alive may be sitting right in front of you.
Suppose credit cards carried you through a six month income interruption.
Your income has recovered.
Three years later, the balance remains.
The income interruption created the debt.
It isn’t necessarily keeping the debt alive today.
Now the problem could be high interest. It could be new charges. Perhaps there is no repayment strategy. Maybe you’re sending extra money to the card, then using the card again when irregular expenses appear.
That last pattern is particularly important.
You can be aggressively paying debt while repeatedly recreating it.
The problem may not be motivation.
Your financial system may have no shock absorber.
Before You Throw Everything at Debt, Look at Your Savings
Imagine this.
You have $1,500 left at the end of the month.
You’re determined to get rid of your credit card debt. Every dollar goes to the card.
It feels fantastic. Then the car needs a repair.
You need $1,200.
There is no available emergency reserve.
So the repair goes where? Back on the card.
Now you’re frustrated because you were doing everything right. But the repayment strategy never accounted for ordinary life. That doesn’t mean everyone needs to stop paying debt and stockpile cash. It means debt repayment and financial resilience belong in the same conversation.
Your plan has to survive contact with your actual life.
Question Three:
What Is This Debt Costing You Now?
Interest matters.
But interest is not the only cost.
Debt also occupies cash flow.
Suppose your debt payments total $850 every month.
That money currently has a job.
It goes backward.
Now ask a different question:
What could that $850 eventually become?
Part of an emergency reserve?
An investment?
Retirement contributions?
A home fund?
Business capital?
Travel?
Education?
More breathing room every month?
Debt repayment becomes more interesting when the finish line isn’t merely zero.
Zero is important.
But zero is the doorway.
The bigger question is what you build once the payment belongs to you again.
Give the Payment Its Next Job Before You Finish
Try this.
Write down your current monthly debt payment.
Now complete this sentence:
When this payment belongs to me again, I want it to ____________.
Do not wait until the final payment to decide.
Without a next assignment, newly available cash has an impressive ability to disappear into ordinary life.
Give it somewhere to go.
Maybe you currently send $700 to debt.
When the debt disappears, perhaps $500 automatically begins investing and $200 goes toward travel.
Your answer can be different.
The point is intentionality.
You aren’t simply escaping debt.
You’re recovering financial capacity.
Question Four:
What Needs to Change?
This is where understanding becomes responsibility.
“Debt isn’t always a character flaw” does not mean:
Don’t worry about it.
It means stop wasting energy trying to determine whether you’re a good person and use that energy to understand the financial problem.
Once you understand it, something may need to change.
Your spending may need to change.
Your income may need attention.
You may need emergency savings.
A family boundary may need to become clearer.
Your business and personal finances may need separation.
Perhaps you need automatic payments.
Maybe you need professional financial guidance.
Or perhaps nothing dramatic is wrong.
Your strategy may already be working.
The balance is declining. You’re no longer adding debt.
Your savings are improving.
You simply haven’t reached the finish line yet.
Do not confuse unfinished with failing.
What If the Debt Really Was Your Fault?
Then own that too.
There is enormous power in being able to say:
“I made that decision.”
No elaborate defense.
No self-destruction either.
You bought the car you couldn’t comfortably afford.
You spent because you were unhappy.
You ignored the card.
You let lifestyle creep take over.
You kept rescuing people.
You made a business decision that didn’t work.
Fine.
What did you learn?
What system exists today that did not exist then?
That is the useful part.
A woman can be paying for an old decision while becoming excellent with money today.
Those realities can coexist.
High Income Can Actually Make Financial Problems Easier to Hide

When money is extremely tight, financial problems demand attention quickly.
Higher earners can sometimes carry inefficient financial systems for much longer.
There may be enough cash flow to make every payment.
Enough available credit to absorb another expense.
Enough income to recover from an expensive month.
Nothing feels catastrophic.
So the underlying problem remains.
That’s why “I can afford the payment” is not always the most useful standard.
Ask what the payment is preventing you from owning, building or choosing.
A payment can be affordable and still be expensive to your future.
Try the 15 Minute Debt Autopsy
Set a timer.
Fifteen minutes.
Choose one debt.
Write down:
1. What created it?
Do not clean up the story.
2. What is keeping it alive today?
Look for the mechanism.
3. What is it costing me now?
Include the monthly cash flow, not only interest.
4. What needs to change?
Choose one concrete change.
Then add a fifth line:
When this payment belongs to me again, it will____________________.
Stop there.
You don’t need to fix your entire financial life tonight.
You need enough clarity to make the next decision better than the last one.
Five Moves You Can Make This Week

1. Put every debt in one place
For each debt, record the current balance, minimum payment and interest rate.
No judgment.
Get the information.
2. Find the debt that keeps returning
If you pay a card down and repeatedly use it again, investigate why before blaming your discipline.
3. Review your emergency reserve
Ask what would happen if a $1,000 or $2,000 unexpected expense arrived this month.
The answer tells you something important about your financial resilience.
4. Decide what one payment will become
Choose one debt and assign its future payment a new job.
5. Ask the question you’ve been avoiding
If you don’t understand something, ask.
Confusion gets expensive when embarrassment keeps it private.
You Don't Have to Bring Your Numbers Into the Room
This is one reason I created Financial Feminism.
Women need a place to talk about money without pretending they already understand everything.
You don’t need to join the community and announce how much debt you have.
You don’t need to share your salary.
Nobody needs your credit score.
Bring your question.
Maybe it’s:
Should I save while paying debt?
Should I invest?
Which debt should I tackle first?
How do I stop using my credit card?
How much emergency savings do I need?
How do I tell my family I can’t keep paying?
Why do I make good money and still feel behind?
Those conversations matter.
JOIN THE FREE FINANCIAL FEMINISM COMMUNITY
You don’t have to bring your numbers into the room. Bring your questions.
One Last Thing
Debt can tell you what happened.
It can tell you what you owe.
It can show you where your money is going today.
But it does not get to decide what happens next.
That decision still belongs to you.
And that is where ownership begins.

LISTEN NEXT
Listen to Debt Is Not Always a Character Flaw: What Happens When Life Costs More Than Your Plan on Financial Feminism.
- LISTEN

GET THE RESOURCE
Download The Debt Autopsy™ free inside the Financial Feminism Community.
- DOWNLOAD
FAQ
A higher income can improve repayment capacity without automatically eliminating existing balances or the behaviors and circumstances maintaining them. Interest, recurring credit use, increased expenses, insufficient emergency savings and prior debt can all remain after income increases.
A recurring credit card balance can indicate that the underlying expense pattern remains. Review whether credit is being used for emergencies, irregular expenses, recurring spending or monthly expenses that exceed available cash flow.
The answer depends on the debt, interest rate, income stability, available savings and personal circumstances. Maintaining accessible savings can help prevent an unexpected expense from immediately creating new debt. Individual financial advice may be appropriate for more complex decisions.
Yes. A debt balance alone does not describe every current financial behavior or the circumstances that created the balance. Someone can be actively reducing debt, saving and improving financial habits while still carrying debt.
The Debt Autopsy™ is a Financial Feminism framework created by Dr. Tonika Bruce. It asks four questions: what created the debt, what is keeping it alive, what it is costing now and what needs to change.
Start with information. List balances, minimum payments and interest rates. Then choose one debt and identify what created it and what is maintaining it today. If the situation is complex or unmanageable, consider qualified professional guidance appropriate to your circumstances.
Separate the financial facts from conclusions about your identity. Acknowledge decisions that need changing, identify the circumstances and behaviors contributing to the balance and focus on the next action available to you.
That decision depends on factors including debt costs, employer benefits, available emergency savings, investment time horizon and personal circumstances. Avoid treating either “pay every debt first” or “always invest first” as a universal rule.
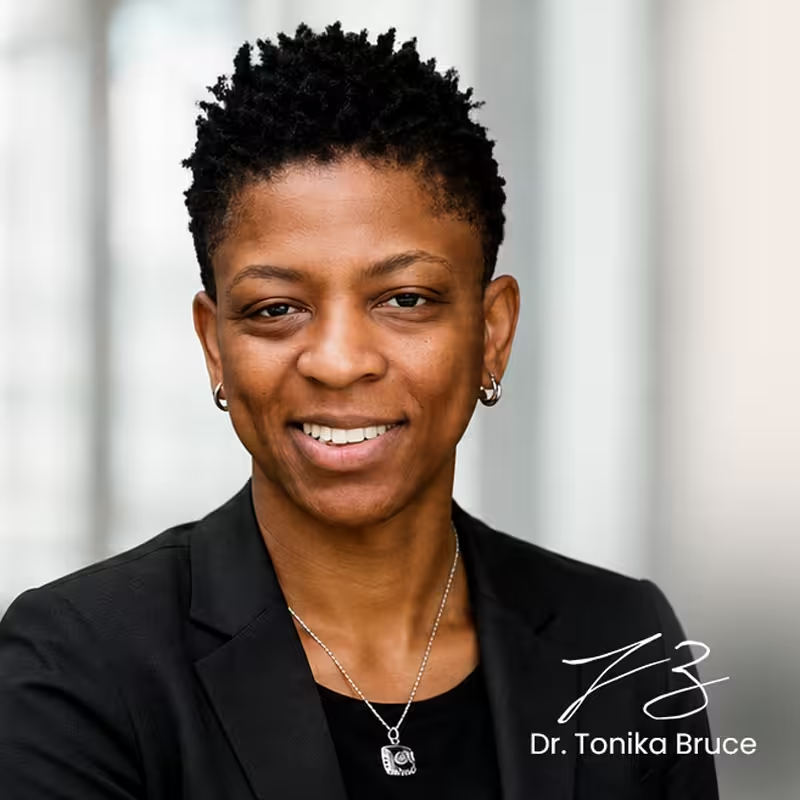
Dr. Tonika Bruce
Dr. Tonika Bruce is an entrepreneur, business strategist, leadership expert and host of Financial Feminism. Her work focuses on helping women connect income with ownership, stronger decisions and greater financial options.
- Explore Financial Feminism
- Listen to the Podcast
- Join the Community